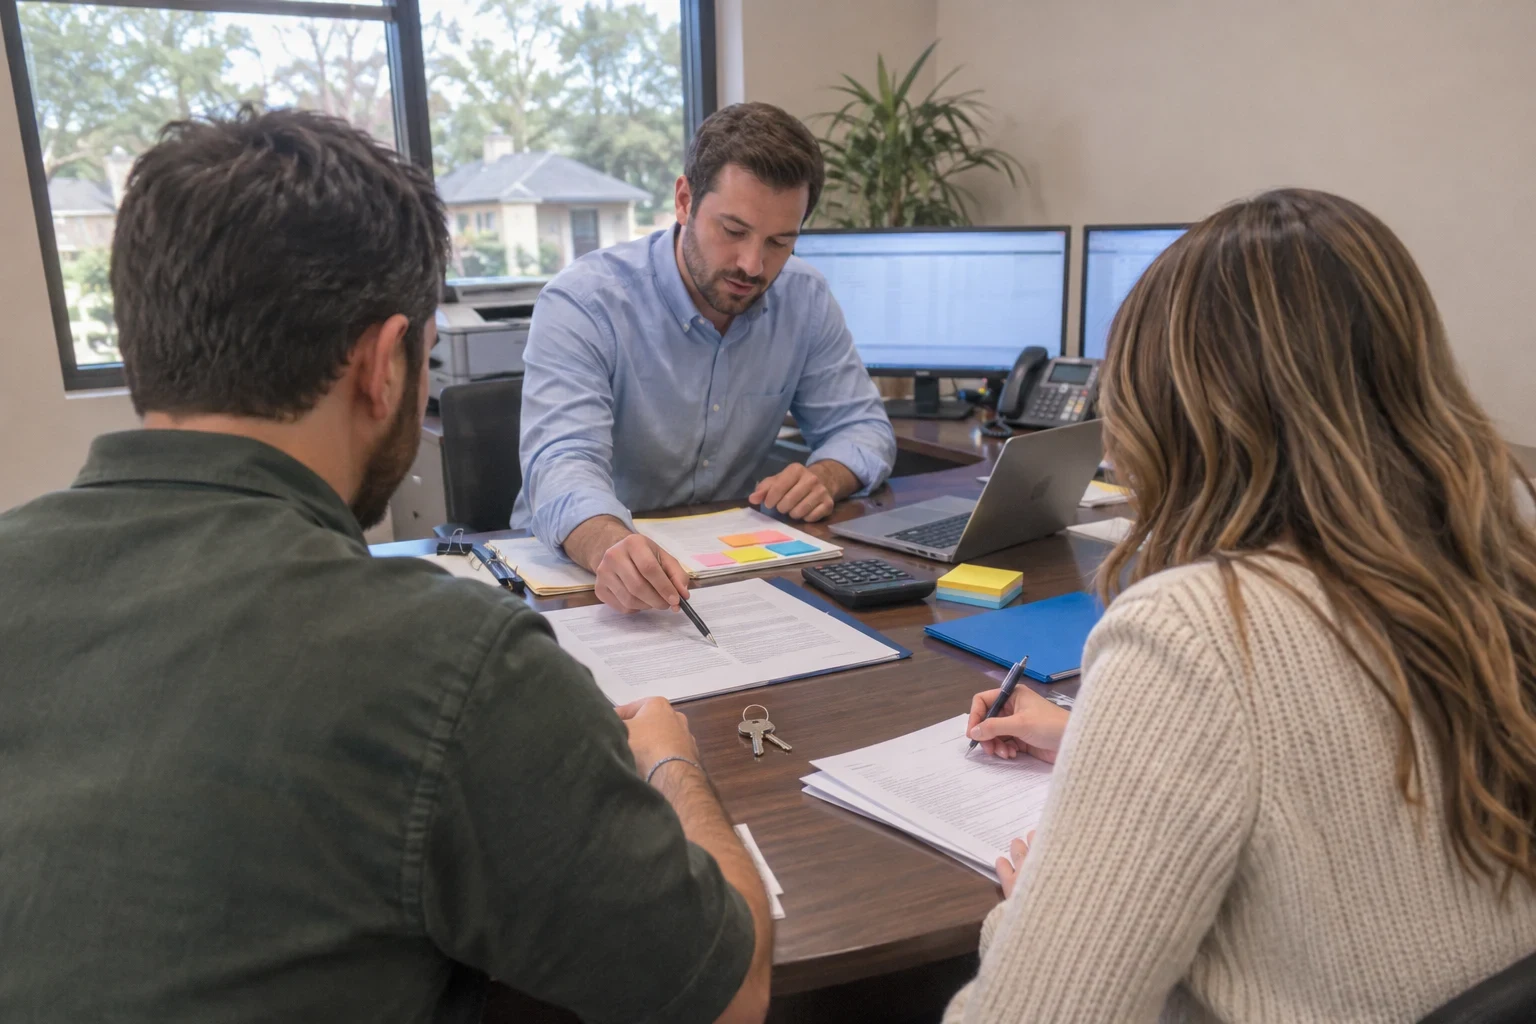
Home Loans in Sunset Valley, Guided by One Loan Officer
From a first purchase to a VA buy or an equity refinance, one loan officer handles your file from the first question to closing. We arrange conventional, FHA, VA and USDA home loans, along with HELOCs, bank statement loans and bridge loans, for borrowers in Sunset Valley, Buda and Lakeway, in person or by phone and video.
- Same loan officer to closing
- Pre-qualification over the phone
- In person or remote
- Every cost explained in writing
Home Loan Programs We Offer
With 11 years in the mortgage industry, and NMLS licensed for 10 years, we have placed borrowers in nearly every kind of mortgage. Conventional loans, FHA loans, VA loans and USDA loans cover most purchases and refinances. A HELOC lets you draw on equity you have already built. For borrowers whose finances don't fit a standard file, we offer bank statement loans, hard money loans and bridge loans.
Conventional Loans
A conventional home loan for buyers with steady income and solid credit, with one loan officer handling your file from first call to closing.
FHA Loans
FHA financing backed by the Federal Housing Administration, with smaller down payments and more flexibility on credit, handled by one loan officer from first call to closing.
VA Loans
Zero-down VA financing for eligible veterans and service members, with one loan officer handling eligibility, appraisal and closing.
USDA Loans
No-down-payment financing for buyers purchasing in USDA-eligible areas, with one loan officer checking the address, the income limit and every step to closing.
HELOC
A revolving line of credit secured by the equity you've built, so you draw funds when a cost arrives and keep your first mortgage rate in place.
Hard Money Loans
Short-term financing secured by the property itself, for investors who need to buy, renovate and resell or refinance on a clear timeline.
Bank Statement Loans
For self-employed borrowers whose tax returns understate what they earn, we qualify you on 12 or 24 months of deposits instead.
Bridge Loans
Short-term financing that taps the equity in the property you own now, so the down payment on your next purchase does not have to wait for a sale.
Why Borrowers Choose to Work With Us
Processors, underwriters, appraisers and title officers all touch a mortgage. We place one person between you and every one of them, so there is never a question of who to call or what comes next.
- 01
One loan officer, every step
Whoever answers your first call also reviews your documents, orders the appraisal and sits with you at closing. There is no handoff after the application, and you never have to tell your story a second time.
- 02
Experience behind every file
Our work rests on 11 years in the mortgage industry, and we are NMLS licensed for 10 years. Over that stretch we've learned where loans usually slow down, and we prepare for those points early so a rate lock or closing date isn't put at risk.
- 03
Programs compared side by side
We review more than one loan type for you. A first-time buyer may qualify for FHA and conventional financing alike, and the better pick depends on mortgage insurance, down payment and how long you expect to stay. We set out the options and the decision stays with you.
- 04
Numbers you can read
Each option shows its rate, monthly payment and closing costs, explained line by line. If underwriting changes anything, you hear from us what changed and the reason.
- 05
Meet the way that suits you
Visit our office, or run the entire loan by phone and video. Plenty of borrowers mix the two.
What Moves Your Rate and Closing Costs
Lenders set terms by weighing risk, so two borrowers asking for the same amount can see different numbers. When you know which levers matter, you can spend your preparation where it counts. Each of these comes up during your pre-qualification conversation.
Once you apply, you receive an official Loan Estimate with the rate, payment and closing costs for your loan. We sit down with it together, line by line, before you agree to anything.
- Credit scores and history
- Scores matter, and so does what sits behind them. One late payment or a card near its limit can nudge pricing, and paying a single balance down before you apply sometimes changes the result in a way you can see.
- Down payment or existing equity
- A larger down payment, or more equity in a refinance, lowers the lender's exposure. It also decides whether mortgage insurance is required and how soon it can come off.
- The program you choose
- Conventional, FHA, VA and USDA loans each have their own fee structure, insurance rules and rate behavior. Bank statement, hard money and bridge loans price on their own terms, since they lean on deposits or on the property rather than standard income documents.
- Debt-to-income ratio
- We set your monthly obligations against your verified income. When that ratio is lower, more programs open up and the terms on offer often improve.
- How the property will be used
- A place you live in full time is priced one way, while a vacation property or a rental is priced another. Condominiums and buildings with two to four units can bring extra guidelines of their own.
- Rate lock and points
- Rates change every day. The moment you lock, the length of the lock and any points paid to lower the rate all shape the final figures.
A Mortgage Office Built Around One Relationship
Home Loans Sunset Valley works with buyers, veterans, self-employed borrowers and investors across the Austin area. We set the office up so that a single loan officer carries each file from beginning to end. It is a slower way to grow a business, and a calmer way to get a mortgage.
We take time on the first conversation. Before we suggest a program, we want to know how long you plan to stay, how steady your income is and what monthly payment you'd be comfortable with. A good loan fits the borrower first and the guidelines second.
You can read more about how we work on our About page, or browse each loan program on the Services page.
- License
- NMLS licensed for 10 years
- In business
- 11 years in the mortgage industry
How a Home Loan Comes Together
Here is the usual path from your first call to closing. Each step shows what we ask of you and what we handle on our side.
- 1
Pre-qualification call
We talk through your goals, income, savings and the type of property you have in mind. By the end of the call you have a sensible price range and a short list of programs worth a closer look.
- 2
Application and pre-approval
You gather pay stubs, tax returns, bank statements or other records, depending on the program. We verify them and, once you qualify, prepare a pre-approval letter for sellers and agents.
- 3
Loan Estimate and rate lock
Once you have a signed contract on a property, we prepare your Loan Estimate and talk through the right time to lock your rate. Nothing moves forward until you approve the terms.
- 4
Appraisal and underwriting
We order the appraisal and hand your file to the underwriter. If they need anything more, we call you ourselves to explain what is needed and why.
- 5
Closing
We review your Closing Disclosure with you ahead of time and coordinate the details with the title company. On closing day you sign, and the keys or the funds are yours.
Common Borrower Questions
- How is pre-qualification different from pre-approval?
- Pre-qualification is an early estimate of what you can borrow, based on the income, debts and savings you describe to us on the phone. Pre-approval comes later, after we have verified your documents and reviewed your credit. Sellers and agents treat a pre-approval letter as the stronger signal, so most buyers start with pre-qualification and take the next step once they are ready to make offers.
- What down payment will I need?
- It varies by program. VA loans and USDA loans allow eligible borrowers to buy with nothing down, FHA loans accept a smaller down payment, and conventional loans have several options. We will walk you through how each one affects your monthly payment and whether mortgage insurance applies.
- Does looking at my options hurt my credit?
- No credit is pulled during a pre-qualification conversation. When you are ready for pre-approval, we tell you beforehand that a credit check is next and explain what it involves. We run nothing without your go-ahead.
- I work for myself. Is a home loan still possible?
- In many cases, yes. A good number of self-employed borrowers qualify for conventional or FHA financing using their tax returns. When write-offs make your taxable income look lower than what you actually earn, a bank statement loan can rely on your deposits instead. We look at both paths together.
- How long until closing?
- That depends on the loan program, the appraisal and how quickly documents come back to us. On the first call we sketch out a realistic timeline for your loan, and we keep you updated as each stage is cleared.
- Should I refinance or open a HELOC?
- A refinance replaces your current mortgage with a new loan, which makes sense when it brings a lower rate or a better term. A HELOC is a separate line of credit you draw on as needed, and it often suits borrowers who want to hold on to the rate they already have. We compare the two for you side by side.
- Will I have to come into the office?
- Not unless you want to. You can meet us in person in Sunset Valley, or handle the entire loan by phone and video. Many borrowers visit once for the first conversation and complete everything else remotely.
Communities We Serve
Sunset Valley is our base, and our borrowers come from all around it: Austin, Shady Hollow, Barton Creek, West Lake Hills, Lakeway, Steiner Ranch, Bee Cave, Belterra, Buda and Hornsby Bend. A buyer in Steiner Ranch and a veteran refinancing in Buda get the same loan officer and the same steady process. Most of the work happens by phone and video, so the drive to our office is optional.
- Sunset Valley
- Shady Hollow
- Barton Creek
- West Lake Hills
- Austin
- Lakeway
- Steiner Ranch
- Buda
- Hornsby Bend
- Bee Cave
- Belterra
Buying somewhere else in Texas? Mention it when we talk and you'll get a straight answer on whether we can take the loan. The Service Areas page shows where we lend most often.
Start With a Conversation
Tell us what you are hoping to buy or refinance, and we'll walk you through the programs that fit and what you'd likely qualify for. The loan officer you speak with is the one who will see it through to closing.